The IUL Guide
Thinking Aboutan IUL?Start Here.
Get a simple guide to understand how Indexed Universal Life works: what it may provide, and where its limitations are.
- Build protection
- Pursue growth
- Create opportunity
Complimentary
Get the IUL Guide
7 things to understand before using an IUL in a retirement strategy.
Inside the guide
7 Things to Understand Before Using an IUL
Indexed Universal Life is often misunderstood. Here’s a preview of what the guide walks through, in plain English.
- 01
It’s Life Insurance First
An IUL is permanent life insurance with a death benefit. It is not a stock-market investment, and it should start with a real need for protection.
- 02
How Index Crediting Works
Your cash value isn’t invested in the market directly. Interest is credited based on the performance of an index, such as the S&P 500®, over a set period.
- 03
Caps and Participation Rates
Upside is limited. Caps and participation rates set how much of an index gain is credited, and the insurer can change them over time.
- 04
Floors Protect Against Index Losses
Many policies have a 0% floor, so a down year for the index isn’t credited as a loss. Policy charges are still deducted in those years.
- 05
Policy Charges Matter
Cost of insurance, administrative fees and rider charges reduce cash value, especially in the early years. Understand them before you commit.
- 06
Loans Give Access, With Trade-offs
You can borrow against cash value, but loans accrue interest and reduce the death benefit. A poorly managed loan can cause a policy to lapse.
- 07
Many Values Aren’t Guaranteed
Illustrations are hypothetical. Results depend on how the policy is funded, credited and reviewed over time, so it needs ongoing attention.
Get All Seven, Explained.
Download the full guide free and keep it for your next conversation with your family or advisor.
Get the Free Guide
The third bucket
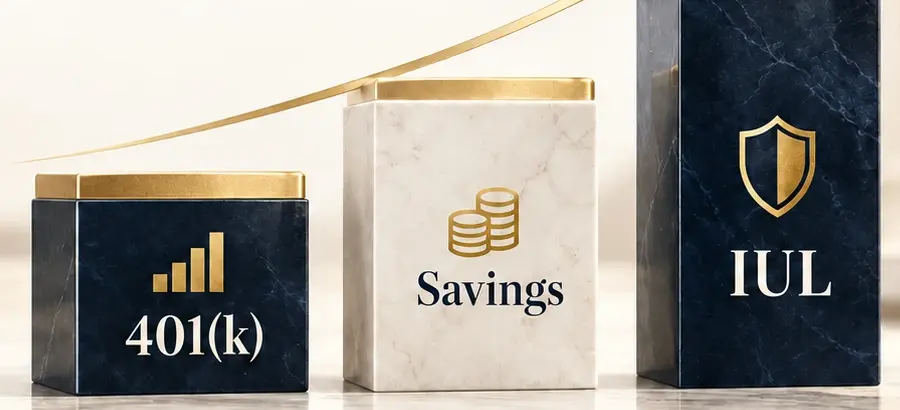
You Have a 401(k). You Have Savings. What’s Your Third Bucket?
Your 401(k) doesn’t have to be your entire retirement strategy. Some people use properly structured permanent life insurance as another component of a long-term financial plan.
- Bucket 1Your 401(k)Tax-deferred growth and often an employer match. Withdrawals in retirement are generally taxed as income.
- Bucket 2Your SavingsLiquid and accessible for emergencies and near-term goals, with growth that’s taxed along the way.
- Bucket 3An Insurance StrategyProperly structured permanent life insurance can add a death benefit plus cash value that may be accessed later.
Tax diversification
What If Taxes Are Higher When You Retire?
Retirement planning isn’t only about how much you accumulate. It’s also about how different assets may be treated when you eventually need income. Is your retirement income diversified by tax treatment?
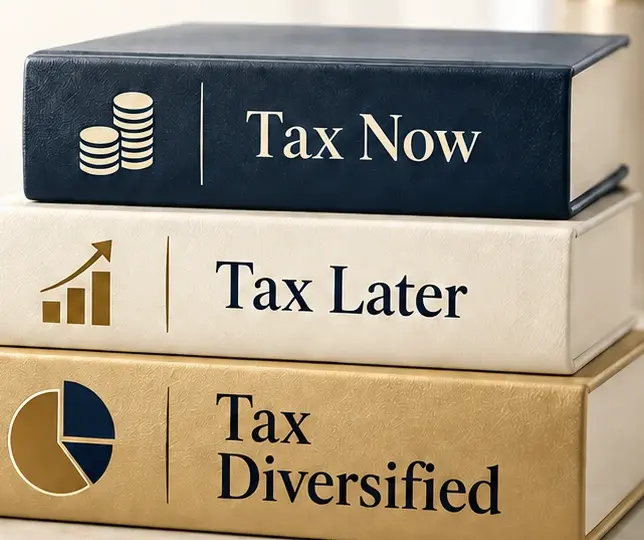
- Tax NowSavings, CDs and brokerage accounts. Growth is generally taxed as you go.
- Tax Later401(k)s and traditional IRAs. Contributions are often pre-tax, and withdrawals are taxed as income.
- Tax-AdvantagedRoth accounts and properly structured life insurance, where qualifying distributions or policy loans may be received income-tax-free.
Who we work with
Planning Built Around Your Situation
Maxed-Out 401(k) Savers
You’re already funding your employer plan and want to know what else is available.
Business Owners
Much of your net worth is tied up in your company. Build something outside it.
Healthcare Professionals
You care for everyone else. Make a plan for your own future, too.
Families
You want lasting protection for the people who depend on you, with long-term flexibility.
Meet your guide
Jaden Gallion
Insurance Professional · J Gallion Financial
Jaden helps families, professionals and business owners understand how life insurance strategies like Indexed Universal Life may fit alongside the retirement accounts they already have.
His approach is education first: how a policy works, what it costs, what isn’t guaranteed, and whether it makes sense for you at all. You’ll get straight answers and no pressure.
- Get the GuideLearn the basics on your own time.
- Have a ConversationA short, no-cost educational review.
- Decide What FitsMove forward only if it makes sense.
Common questions
Straight Answers
Is an IUL an Investment?
No. An IUL is a life insurance policy. Its cash value earns interest linked to an index, but your money is not invested in the stock market, and you don’t own shares of the index.
Can I Lose Money in an IUL?
Index crediting typically has a floor, so a market decline isn’t credited as a loss. However, policy charges continue to be deducted, so cash value can decline, especially if the policy is underfunded or loans aren’t managed.
Who Is an IUL a Good Fit For?
It may fit people who need permanent life insurance, have a long time horizon, and can fund the policy consistently. It isn’t right for everyone, and it shouldn’t replace an emergency fund or employer match.
What Does the Review Cost?
Nothing. The guide and the conversation are educational and free, with no obligation to buy anything.
Strategy Today. A Brighter Tomorrow.
Get your complimentary IUL Guide and see whether Indexed Universal Life belongs in your plan.
Get the Free Guide